You are on the Investment solutions website for advisors & wealth management firms.
Browse more Fidelity websites here.
The headline number of 29,000 new jobs was disappointing and represents a meaningful slowdown from the stronger payroll growth recorded earlier in the expansion.
Numbers such as this would typically raise concerns about slowing economic momentum since employment and income growth are key drivers of consumer spending, which accounts for about two-thirds of the U.S. economy. The labor-supply backdrop also matters. Slower population growth, an aging workforce, and potentially slower growth in immigration-related labor supply mean the economy may require fewer monthly payroll gains to keep unemployment from spiking. In this context in today’s environment, numbers that might appear weak amid a faster-growing labor force may not be cause for major concern.
Despite weaker hiring, other parts of the economy remain relatively resilient. Several crosscurrents help explain why the payroll headline may overstate the deterioration:
The measures of hiring demand reinforce this distinction. The JOLTS openings rate has fallen sharply from its 2022 peak but remains near 4.3%,2 while the share of small businesses reporting unfilled positions has also retreated from post-pandemic highs and remains around 30%. In other words, employers are posting fewer jobs and finding it easier to hire, but demand for workers has not disappeared. That helps reconcile September’s modest 29,000 payroll gain with continued economic resilience: weaker hiring reflects both cooler demand and a less acute labor shortage, rather than a surge in layoffs.
For decades, economic growth has relied on one of two things: More workers and an increase in production per worker. The post-pandemic recovery was largely driven by more workers. With labor supply growing more slowly, the next phase of expansion may depend increasingly on productivity. Across industries, executives are increasingly asking a new question: Can technology enable existing employees to be more productive before additional hiring becomes necessary?
This is where AI comes into play. The introduction of AI may not lead to widespread job displacement. Instead, it may take the form of productivity gains that allow businesses to sustain growth while expanding their workforce at a more gradual pace, in our view.
AI may automate pieces of the job, but that is very different from replacing the job entirely. The near-term AI labor-market story may be augmentation first, displacement later.
Technology and media, along with finance and insurance, have the highest rates of AI use, but together represent a relatively modest share of overall employment (Exhibit 1). By contrast, large sectors such as health care and retail fall closer to the middle of the adoption spectrum, while accommodation and food services continue to lag. That pattern argues against assuming an immediate, economy-wide employment shock: AI’s first effects are likely to emerge in digitally intensive sectors and specific tasks, with wider labor market consequences hinging on how rapidly adoption diffuses across the broader economy.
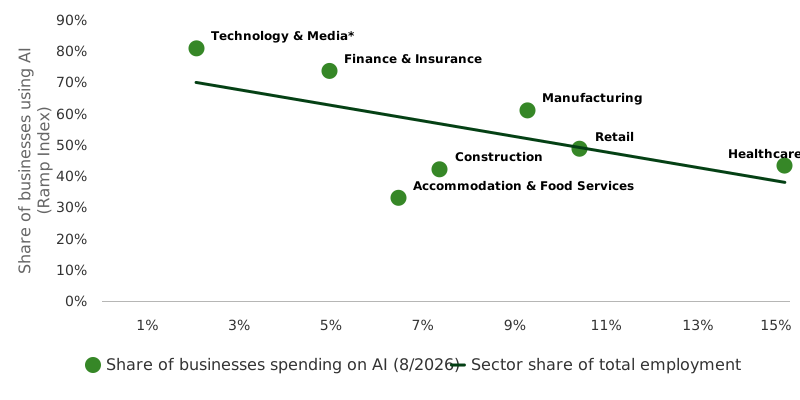
Note: Technology and media sector is mapped to the information sector. The Ramp index may slightly overestimate AI usage based on the samples used. Source: Macrobond, Ramp (Ramp AI Index), U.S. Bureau of Labor Statistics, Fidelity Investments (AART), as of 9/30/26.
The chart above also measures adoption, not realized productivity gains. The next test is whether broader AI use translates into measurable improvements in output, margins, and revenue per employee. If AI allows financial advisors to automate administrative workflows and software developers to write code faster, economic output can continue growing even as employment growth in those industries slows.
The productivity opportunity may be significant today, but its transformative potential depends on adoption spreading to sectors that employ a larger share of the workforce. If those gains fail to materialize, slower hiring could weigh on income, consumption, and earnings.
Investors often assume slower hiring leads directly to weaker earnings. But if productivity gains, slower labor-force growth, and task-level AI augmentation offset labor softness, earnings growth could remain more resilient than economic data alone might suggest. That distinction matters to investors. Companies that grow revenue with fewer incremental hires may benefit from stronger margins and earnings growth. Potential beneficiaries may appear across sectors—including technology, financials, health care, industrials, and select consumer businesses. The opportunity is likely to be company-specific, favoring firms that can demonstrate adoption and measurable operating leverage rather than sectors with AI exposure in name only.
The weaker payroll report may reinforce expectations for a less hawkish policy environment, but slower labor supply complicates the message: The economy may need fewer jobs to remain balanced. A gradually cooling labor market could support duration if bond yields decline, while current yields continue to provide income if rates remain elevated.
Most investors have focused on companies building AI. The next phase may broaden toward AI users—companies that can demonstrate higher revenue per employee, improving margins, or faster output growth without relying primarily on workforce reductions.
The labor market is slowing, but slower hiring need not signal recession when coupled with a slowly expanding labor force. For investors, jobs alone are no longer the signal to watch. The focal point should be whether productivity can keep economic growth and profits advancing even as hiring slows.

1. U.S. Bureau of Labor Statistics, https://www.bls.gov/news.release/pdf/empsit.pdf
2. JOLTS openings rate is the percentage of jobs that employers are actively trying to fill. JOLTS stands for the Job Openings and Labor Turnover Survey conducted by the U.S. Bureau of Labor Statistics.
The information contained herein is general in nature and should not be construed as legal or tax advice. This material is not intended to provide, and should not be relied on for, tax, legal, investment, or accounting advice. Tax laws and regulations are complex and subject to change. You should consult your own tax, legal, investment, and accounting advisors before engaging in any transaction.
Some of this information is forward-looking and is subject to change.
Views expressed are as of the date indicated, based on the information available at that time, and may change based on market and other conditions. Unless otherwise noted, the opinions provided are those of the authors and not necessarily those of Fidelity Investments or its affiliates. Fidelity does not assume any duty to update any of the information.
Diversification does not ensure a profit or guarantee against a loss.
Investment decisions should be based on an individual’s own goals, time horizon, and tolerance for risk.
These materials are provided for informational purposes only and should not be used or construed as a recommendation of any security, sector, or investment strategy.
Stock markets, especially foreign markets, are volatile and can decline significantly in response to adverse issuer, political, regulatory, market, or economic developments.