SERIES
Insight & Outlook: Fidelity Market Signals Weekly
Introducing new weekly insights from Fidelity Institutional's (FI) Capital Markets Strategy Group covering the latest market trends, economic developments, and key factors shaping investment decisions—all to help you and your clients navigate the markets with confidence.
The underappreciated opportunity in today's stock market
Looking beneath index returns to understand what’s really going on in the market may matter more now than it has in decades.
Why have stock correlations fallen to unusually low levels across major equity markets? This reflects an increase in the importance of company-specific fundamentals. Even as a handful of mega-cap stocks continue to drive index returns, performance beneath the surface has become increasingly differentiated. Companies with strong earnings, healthy balance sheets, and durable competitive advantages are being treated differently than those facing slowing growth or elevated debt burdens. For advisors, this may be an opportune time to look beyond headline index returns and reassess whether underperforming holdings remain supported by their underlying fundamentals.
Despite solid returns for much of 2026, investors still face plenty of uncertainties. Elections, geopolitics, interest rates, elevated valuations, concentrated market leadership, and lofty earnings expectations all suggest that headline index returns may tell only part of the story.
The Capital Markets Strategy Team, however, maintains a constructive outlook. We continue to see long-term tailwinds and attractive opportunities in large cap stocks, even if returns look less stellar than they have in the recent past.
An underappreciated reason
Our optimism is driven in part by the fact that stocks are increasingly moving on their own merits, and doing so to a greater degree than at most points over the past three decades.
As Exhibit 1 shows, equity return correlations have fallen across the board over the past five quarters and are now historically low.
Exhibit 1: Stock correlations have declined for major indexes
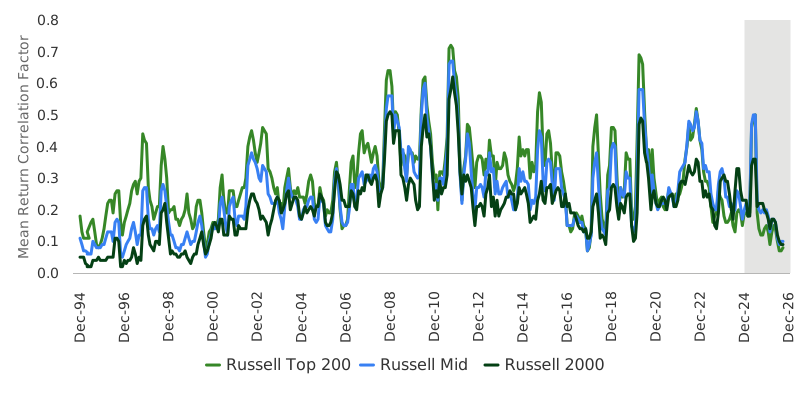
Past performance is no guarantee of future results. 60D = 60 days. Correlation analysis above uses trailing 60 days of daily returns. Source: Bloomberg Finance L.P. and Fidelity Investments Equity Quantitative Research, as of 9/30/26.
- Major U.S. indexes now sit well below their historical average since 1994, placing current correlations in roughly the lowest quartile of observations.
- Correlations within the Russell Top 200, S&P 500, and Russell Midcap Index all stand at less than half their historical averages.
At first glance, these findings may seem counterintuitive. Market leadership remains highly concentrated, with a relatively small number of mega-cap companies driving a disproportionate share of index returns. Yet beneath the surface, performance across individual stocks has become increasingly differentiated.
The AI trade is a timely example
The recent sell-off in AI names doesn't mean the theme is failing; it means the theme is growing up. Investors are shifting from capex spend to capex ROI, no longer rewarding heavy spending as a signal of conviction, but looking for evidence that it's turning into cash flow. Companies with similar spending plans have seen very different market reactions as a result.
Earnings season reflects the same discipline. Most S&P 500 companies have beaten estimates, but by the narrowest margins since late 2022. Earnings beats have earned muted rewards while disappointments have been punished sharply. This looks more like valuation discipline than a bubble. Bubbles reward every story equally; this market is separating winners from losers on fundamentals.
The midterm election results fit the same theme. A shift in congressional control is unlikely to move all stocks in the same direction; the impact may be uneven across sectors and companies. Historically, the S&P 500 has also tended to post gains in the year after midterms, regardless of which party won, though past performance is no guarantee of future results.
What is driving portfolio performance?
As outcomes become more dispersed, understanding what is driving portfolio performance may become increasingly important. Advisors may want to look beyond index-level returns and evaluate exposures at the factor, sector, and security levels. Earnings quality, balance-sheet strength, competitive positioning, and durable growth may play a larger role in outcomes than they have in recent years.
As dispersion widens within sectors and across the AI supply chain, selectivity matters more than owning a theme or index, strengthening the case for active management.
In particular, advisors may want to take a fresh look at underperforming holdings. In a market increasingly driven by company-specific fundamentals, the key question is not which stocks have lagged, but why?
For advisors seeking additional perspective, portfolio research resources and investment specialists may help identify what broad market performance can sometimes obscure.
Lower stock correlations cannot tell us where markets go next. They do, however, suggest that broad market trends may be becoming a less complete explanation of what’s really going on in the market.
Previous weekly market commentaries
Concentration risk may merit investors reviewing their allocation to stocks tied to artificial intelligence.
The headline S&P 500 has remained close to its highs, but the calm at the index level masks turbulence underneath.
- Fewer stocks are driving the market advance.
- Mega-cap stocks are doing the heavy lifting.
- The equal-weight market looks less resilient, trailing the cap-weighted index.
Related insights

Featured series

Meet the FI Capital Markets team
The FI Capital Markets Strategy Group synthesizes economic analysis and market outlooks from across Fidelity to provide timely, actionable perspectives for financial advisors and institutional investors.

Russell Midcap® Index is a market capitalization-weighted index designed to measure the performance of the mid cap segment of the U.S. equity market. It contains approximately 800 of the smallest securities in the Russell 1000 Index.
Russell Top 200 Index is a market capitalization-weighted index that measures the performance of the 200 largest U.S. companies in the Russell 3000 Index.
Russell 2000® Index is a market capitalization-weighted index designed to measure the performance of the small cap segment of the U.S. equity market. It includes approximately 2,000 of the smallest securities in the Russell 3000 Index.
The S&P 500 index is a market capitalization-weighted index of 500 common stocks chosen for market size, liquidity, and industry group representation to represent U.S. equity performance.
The information contained herein is general in nature and should not be construed as legal or tax advice. This material is not intended to provide, and should not be relied on for, tax, legal, investment, or accounting advice. Tax laws and regulations are complex and subject to change. You should consult your own tax, legal, investment, and accounting advisors before engaging in any transaction.
Some of this information is forward-looking and is subject to change.
Stock markets, especially foreign markets, are volatile and can decline significantly in response to adverse issuer, political, regulatory, market, or economic developments.
Views expressed are as of the date indicated, based on the information available at that time, and may change based on market and other conditions. Unless otherwise noted, the opinions provided are those of the authors and not necessarily those of Fidelity Investments or its affiliates. Fidelity does not assume any duty to update any of the information. Diversification does not ensure a profit or guarantee against a loss. Investment decisions should be based on an individual’s own goals, time horizon, and tolerance for risk. These materials are provided for informational purposes only and should not be used or construed as a recommendation of any security, sector, or investment strategy. Stock markets, especially foreign markets, are volatile and can decline significantly in response to adverse issuer, political, regulatory, market, or economic developments.