SERIES
Insight & Outlook: Fidelity Market Signals Weekly
Introducing new weekly insights from Fidelity Institutional's (FI) Capital Markets Strategy Group covering the latest market trends, economic developments, and key factors shaping investment decisions—all to help you and your clients navigate the markets with confidence.
What could reduce the market’s increasing dependence on AI leaders?
Concentration risk may merit investors reviewing their allocation to stocks tied to artificial intelligence.
The headline S&P 500 has remained close to its highs, but the calm at the index level masks turbulence underneath.
- Fewer stocks are driving the market advance.
- Mega-cap stocks are doing the heavy lifting.
- The equal-weight market looks less resilient, trailing the cap-weighted index.
- Why should investors take note of the reliance on a limited number of stocks? While not inherently a concern, market concentration like investors are experiencing today has been associated with many technology advances throughout history. However, it may be problematic if it increases dependence on a single theme, possibly undermining what on the surface seems to be a well-diversified portfolio.
- What could reduce the market’s dependence on AI leaders? Valuation pressures and stronger earnings growth in sectors not tied to AI each could play a role.
- What should investors be thinking regarding this AI-driven market concentration? Rather than trying to predict a rotation, investors may want to ask whether portfolios remain diversified across sectors, styles, regions, and sources of return.
- How might advisors frame a portfolio conversation with their clients? We are not suggesting investors should abandon mega-cap growth. Rather, it’s a good time to meet with your clients to make sure one theme, sector, or group of companies has not quietly become most of their portfolios.
It’s no secret the equity market continues to be led by a small group of large companies: This year, it has been more concentrated among the top 10 components than at any time in the past 100 years (Exhibit 1).
Exhibit 1: Top 3,000 stocks market concentration % (top 10 stocks).
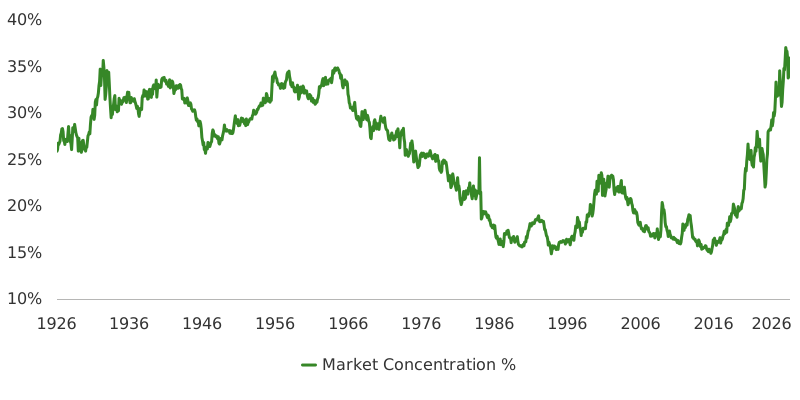
Analysis based on Fidelity top 3,000 U.S. stocks by market capitalization. Source: Haver Analytics and Fidelity Investments, as of 5/31/26.
As mega-cap growth and AI-linked stocks have widened their lead over most S&P 500 components in recent weeks, the broadening that we expected in 2026 has yet to materialize in a durable way. Investors have repeatedly expected market leadership to broaden, only to see AI-related leadership reasserted, supported by strong earnings growth.
Is the high market concentration really a problem? It hasn’t been. As we’ve written many times, leadership cycles in the past started with a small group of companies tied to a major economic transition (railroads, internet platforms, and more). It’s historically common.
Here’s the potential rub: What happens if AI companies become less dominant contributors to future returns?
As of early October, a string of positive earnings surprises from a handful of companies have supported the market. The opposite could also become true at some point: Earnings that surprise less to the upside could negatively affect the S&P 500.
Also, valuation pressure from higher rates (absent an improving economy) or earnings growth in sectors not as closely tied to AI could reduce the market’s dependence on the mega-cap AI leaders over time.
What could reduce the market’s dependence on AI leaders?
In no way are we arguing that investors should abandon their core equity allocations in a concentrated market.
However, they may need to think more deliberately about diversification. We think a broadening of the historically concentrated market—something we’ve anticipated this year—may still happen for three key reasons:
- Strong earnings growth could eventually expand beyond AI-focused technology.
- Higher rates absent an improving economy could create valuation pressure for the market’s most richly valued companies.
- AI investments could start to shift from infrastructure providers to AI adopters, which include more small cap, mid cap, and international value plays.
What actions should investors take?
If investors haven’t already, it’s likely time to review portfolio diversification with their advisors. Market concentration is increasingly thematic, not just equity-specific. Capital spending, earnings growth, and performance across multiple asset classes are becoming more closely tied to the AI theme. These dynamics extend across public investment-grade fixed income, private equity, credit markets, and real estate.
Even a portfolio that appears well diversified by asset class may still have meaningful exposure to the same underlying AI-related theme.
For extreme portfolios, advisors may want to:
- Trim outsized client positions back toward intended weights.
- Complement market-cap-weighted exposure with more balanced approaches.
- Consider active strategies where dispersion is rising.
- Look at allocation balance by sector, style, and region, not just by asset class.
- Review aggregate AI exposure across client portfolios.
Within equities, advisors might consider whether small and mid cap allocations remain appropriately represented in client portfolios. Many of those components are underrepresented in mega-cap-heavy benchmarks, including regional banks, industrial suppliers, health care services, consumer cyclicals, and domestically focused businesses.
Many of these stocks may also be resilient valuation plays. Dozens of them enter the fourth quarter with lower price-to-earnings ratios, greater sensitivity to financing conditions, and more room for operating leverage if demand remains resilient.
Conclusion
Today's market concentration reflects the extraordinary business success of a small group of companies. Their leadership has been supported by strong earnings growth and continued customer spending.
Could the market broaden from here? It might.
Even if it doesn’t, investors may be underestimating the need for diversification.
Previous weekly market commentaries
Related insights

Featured series
Meet the FI Capital Markets team
The FI Capital Markets Strategy Group synthesizes economic analysis and market outlooks from across Fidelity to provide timely, actionable perspectives for financial advisors and institutional investors.

S&P 500 index is a market capitalization-weighted index of 500 common stocks chosen for market size, liquidity, and industry group representation to represent U.S. equity performance.
The information contained herein is general in nature and should not be construed as legal or tax advice. This material is not intended to provide, and should not be relied on for, tax, legal, investment, or accounting advice. Tax laws and regulations are complex and subject to change. You should consult your own tax, legal, investment, and accounting advisors before engaging in any transaction.
Some of this information is forward-looking and is subject to change.
Views expressed are as of the date indicated, based on the information available at that time, and may change based on market and other conditions. Unless otherwise noted, the opinions provided are those of the authors and not necessarily those of Fidelity Investments or its affiliates. Fidelity does not assume any duty to update any of the information.
Diversification does not ensure a profit or guarantee against a loss
Investment decisions should be based on an individual’s own goals, time horizon, and tolerance for risk.
These materials are provided for informational purposes only and should not be used or construed as a recommendation of any security, sector, or investment strategy.
Stock markets, especially foreign markets, are volatile and can decline significantly in response to adverse issuer, political, regulatory, market, or economic developments.